A personal finance story contrasting lifestyles of spending vs. wealth-building through smart money decisions and investing.
Key Takeaways
- Consistent investing and living below your means build real wealth over time.
- Financing lifestyle purchases can lead to long-term debt and financial stress.
- Understanding the full cost of payments versus total debt is crucial.
- An emergency fund and diversified investments provide financial security during uncertainty.
- Financial freedom is about control over decisions, not just the size of your paycheck.
What the video covers
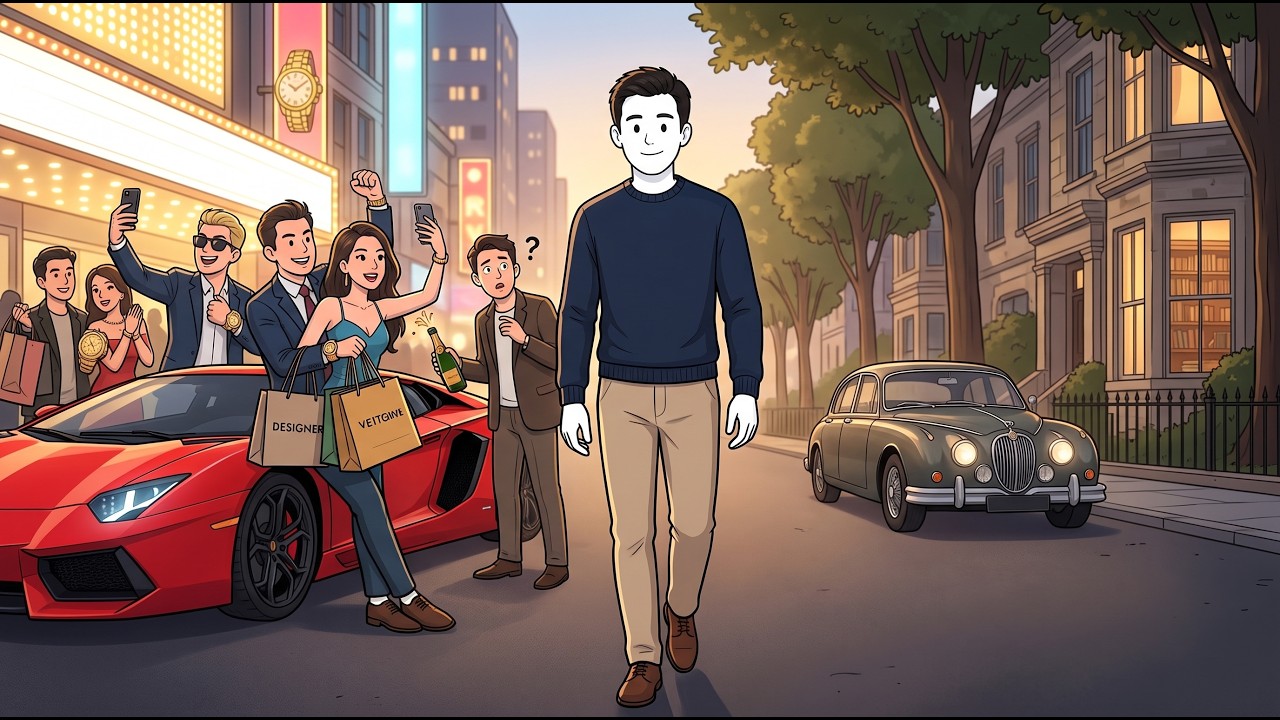
- The video contrasts the financial habits of friends who finance a rich lifestyle with the narrator who builds real wealth through disciplined investing.
- It begins with a scene at a credit union break room highlighting differences in spending and saving behaviors.
- The narrator invests consistently in a Roth IRA and 401k despite a modest salary, while friends finance vehicles, vacations, and home renovations with high-interest debt.
- Over several years, the narrator increases contributions, adds side income, and grows a diversified investment portfolio.
- Friends continue to accumulate debt through financing and credit cards, often unaware of the true cost beyond monthly payments.
- The narrator’s financial stability is tested by a potential job loss, but an emergency fund and investments provide security.
- The video emphasizes the importance of understanding total costs, living below means, and investing for long-term financial freedom.
- It highlights the psychological shift from measuring success by lifestyle to measuring by net worth and financial independence.
- The story ends with the narrator quietly achieving financial freedom while friends remain trapped in a cycle of debt.
- The video encourages viewers to focus on wealth-building decisions rather than consumer-driven appearances.
Chapters
- 00:00Introduction: Contrasting Financial Habits
- 00:50Early Career and Initial Investing
- 01:50Observing Debt Patterns at Work
- 03:20Increasing Income and Investment Contributions
- 05:20Side Income and Growing Portfolio
- 07:00Friends’ Increasing Debt and Financial Struggles
- 07:50Market Growth and Portfolio Milestones
- 09:00Financial Realizations and Mindset Shift
- 09:30The Test: Emergency Fund and Job Security
- 10:00Conclusion: Financial Freedom and Control
Full Transcript — Download SRT & Markdown
Speaker A
It's 6:52 on a Friday evening. You're standing in the break room of the credit union, badge still clipped to your blazer, half a granola bar in one hand.
Speaker A
Rachel is scrolling her phone at the table, laughing. "Cancun in March. Ryan already put the deposit down. Four Afterpay payments. No big deal."
Speaker A
Ryan nods, chewing on a protein bar, keys to a truck that's 11 months old jingling in his pocket. "0% for 18 months. It's basically free."
Speaker A
You smile, say something noncommittal, and finish your granola bar. What they don't know, on your phone under a different app, $140 just left your checking account and landed in a Roth IRA. Balance: $1,620.
Speaker A
You make $34,200 a year processing deposits and cashing checks for people who make triple that.
Speaker A
Ryan makes almost double your salary. Rachel makes more than both of you combined some months with commission.
Speaker A
And yet, on paper, tonight, you are the only person in this room who isn't waiting on a bill to arrive. Nobody in the break room knows that. You don't say it. You just clock out and drive home in
Speaker A
a Honda Fit with 94,000 miles on it. Level 1: The Finance Life. You're 24. The Fit was $6,800 used, paid in full, no loan. It smells like the previous owner's air freshener, no matter how many times you clean it.
Speaker A
Ryan's truck payment is $612 a month. Rachel's Cancun trip, once you do the math on the Afterpay fine print, will cost $1,340 for a $1,180 trip once a missed payment triggers a late fee. Neither of them asked you to
Speaker A
do that math. You didn't offer. At the credit union, you see this pattern from both sides of the counter. A woman finances a $2,400 mattress at 24.99% APR because the store offered 12 months no payments. A man refinances his car
Speaker A
for the third time to lower the monthly payment, extending the loan two more years each time. You process it. You don't judge it out loud, but you notice your 401k has $890 in it. Your employer matches 3%. You've
Speaker A
set your contribution to exactly capture all of it. Nothing more, not yet, because rent is $895 and groceries eat $61.40 out of your account most Sundays. Here's what nobody tells you. Your coworker Marcus says one afternoon, sliding a
Speaker A
rejected loan application into the shredder bin. Everybody in this building is broke at a different price point.
Speaker A
Marcus is 41, drives a 10-year-old Buick. Nobody would guess he's the branch's top earner in commission-based referrals, or that he's been maxing his Roth IRA for 6 years. You don't know his numbers yet. You just remember the sentence. Level two, the gap nobody
Speaker A
sees. Two years pass. You're 26 now. A promotion to personal banker adds $4,300 to your salary, $38,500 total. The raise lands as a direct deposit that's $286 bigger every 2 weeks. You don't upgrade the Fit. You don't move to a nicer apartment. You
Speaker A
raise your 401k contribution from 3% to 8% and open a Roth IRA contribution of $220 a month automatic the same week the raise hits.
Speaker A
Portfolio combined, $13,900. Ryan gets promoted, too, to regional sales. His income jumps to $71,000.
Speaker A
Within 4 months, he's leased a second vehicle, an SUV for weekend stuff, and financed a $3,200 home theater system through the electronic store's 0% plan, which becomes 29.99% retroactive interest the 1 month he's late.
Speaker A
Rachel starts a home renovation. Kitchen countertops $8,900 financed through a contractor's in-house lending arm at 19%.
Speaker A
None of this makes them foolish. Ryan works hard. Rachel is good at her job.
Speaker A
Their spending simply requires their income to keep flowing every month without interruption. Yours doesn't. Not anymore. Not entirely.
Speaker A
"You still driving that thing?" Ryan asks one night, nodding at the Fit in the restaurant parking lot parked next to his leased SUV. "Gets me here," you say. He laughs. You don't explain the rest. Level three, the second income. At
Speaker A
27, you notice something at work. Half the loan applications you process are for debt consolidation. People refinancing car loans into personal loans, personal loans into home equity lines. The debt doesn't disappear. It just changes shape and moves to a
Speaker A
different form. You start freelance bookkeeping on weekends for two small businesses, a flower shop and a mobile detailing company, using the spreadsheet skills your job already requires. $380 a month. Inconsistent, but real. Every dollar of it goes into the brokerage
Speaker A
account untouched by lifestyle. Salary at the credit union climbs to $44,700 after another review. Combined with side income, your monthly investing total reaches $780, 401k, Roth IRA, and brokerage combined.
Speaker A
By your 28th birthday, the number reads $46,300. That's the year Ryan buys a boat, $340 a month financed over 7 years. "It's basically the price of eating out twice a week," he says, and by his math, it is. That's also the year Rachel's credit
Speaker A
card balance crosses $9,600 spread across two cards, both above 22% interest. She doesn't mention the balance. You only know because she asks once, almost casually, if the credit union does personal loans for debt restructuring.
Speaker A
You help her fill out the application. You don't say anything about the boat or the countertops or the Cancun trip 3 years back that's still technically unpaid rolled into a store card that's been carrying a balance ever since. The
Speaker A
strange part is Marcus tells you later watching you process the paperwork. Nobody spends their way into trouble on purpose. They just never see the total, only the payment. Level four, when the numbers flip your 30 salary $52,400 after a move to a slightly larger branch
Speaker A
with more transaction volume. The side bookkeeping work has grown into four clients and $640 a month most of which still goes straight into the brokerage account. Combined investments $107,800.
Speaker A
Then the market has a good year, not spectacular, about 11%, but on a six-figure balance that's real money.
Speaker A
The account grows $14,200 in 12 months. You contributed $9,360 that same year. For the first time the portfolio itself earned more than you put into it. You don't tell anyone. You just notice it quietly the way you'd notice a paycheck landing early. Ryan
Speaker A
meanwhile trades in the truck. Negative equity from the loan gets rolled into the new one. He now owes more on a vehicle than it's worth again. Rachel's debt consolidation loan is current but she's already carrying a new balance on
Speaker A
one of the old cards. Neither of them is careless. They're just running on a treadmill that requires constant income to stay still. You ask Rachel once gently over coffee that costs $4.85 why she doesn't stop and reset. Because
Speaker A
everyone I know lives like this, she says. I don't feel behind. I feel normal.
Speaker A
You think about that sentence for a long time. You realize you used to feel normal too until you stopped measuring yourself against other people's payments and started measuring against your own number. Level five, the test. At 32 the
Speaker A
test arrives and it isn't dramatic. It's a wedding invitation, Rachel's, with a $185 gift expectation, a $420 destination flight, and a bachelorette weekend that runs $610 more. Old you might have put it on a card. New you looks at the
Speaker A
brokerage account, $258,600, and pays cash without blinking because $1,215 against that balance is nothing. The test isn't the wedding. The test comes 3 weeks later when a corporate downsizing rumor spreads through the credit union.
Speaker A
Layoffs unconfirmed, branch consolidations possible. For the first time, you do a different kind of math.
Speaker A
Emergency fund, $22,380. Monthly expenses, roughly $2,900. That's over 7 months of runway without touching a single investment.
Speaker A
Ryan, laid off from his sales role that same quarter, has $1,900 in savings against $4,100 in monthly obligations, truck, boat, lease, cards. He moves back in with his parents within 6 weeks. You keep your job. The rumors pass. But something in
Speaker A
you has shifted permanently. You understand now that the portfolio was never really about the number. It was about which decisions you got to make and which ones got made for you. "When the balance gets big enough," Marc
Speaker A
Between salary, side income, and 4 years of consistent contributions, your combined accounts read $610,400.
Speaker A
That year, the market moves 9%. The gain, nearly $55,000. More than your entire annual take-home pay after taxes. You stare at the statement for a long moment. Then you close the laptop and go make dinner. The reaction is smaller than you expected.
Speaker A
That's the strange part. At $750, this number would have felt like everything. At $610,000, it barely registers as anything at all.
Speaker A
Just quiet confirmation that the system is working exactly as intended. Ryan calls that spring. He's back on his feet. New job, but still paying off consolidated debt from the truck, the boat, the theater system. He asks, carefully, if you'd consider a personal
Speaker A
loan. Friend to friend, not bank to customer. You help him find a lower rate option instead. You don't lend him money. You've learned that lending to people who are still financing a lifestyle rarely fixes the lifestyle.
Speaker A
Rachel, married now, finally pays off the last of the old debt that same year.
Speaker A
Six years after the trip, the countertops, and the wedding that started it. She tells you over coffee that she wishes someone had shown her the real total earlier, not just the payment. You don't say I tried. You just
Speaker A
listen. You're still driving the Fit. It has 148,000 mi now. A crack in the windshield from a highway rock two winters ago that you never bothered to fix because fixing it never felt urgent enough to interrupt anything more important. Your badge
Speaker A
still says the same credit union. A different title beneath it. The coffee is still $4.85.
Speaker A
The granola bars are still in the break room next to the same table where Rachel once laughed about a Cancun deposit and Ryan called an 18-month payment plan basically free. Nobody in that break room today would guess that the combined
Speaker A
accounts under your name cross $610,000, or that this year's market growth alone could cover four years of your rent. You weren't smarter than Ryan or Rachel. You didn't earn dramatically more for most of these years.
Speaker A
Some years, you earned less. You just kept feeding the same quiet system month after month while other systems fed themselves on payments instead of principal.
Speaker A
The fit still runs. The windshield still has its crack. And for the first time since you were 24, none of that feels like something you're waiting to fix once the money finally arrives. The money already arrived. It just never
Speaker A
needed to be seen to be real. If this story felt familiar, if you've ever quietly built something nobody around you could see, I'd love to hear about it in the comments. Hit like if this hit home. Subscribe if you want
Speaker A
more of these. And let me know, is there a financed life in your circle you've noticed but never mentioned out loud?
Speaker A
Thanks for watching. I'll see you in the next one.
Topics:personal financeinvestingwealth buildingdebt managementRoth IRA401kfinancial independencebudgetingside incomemoney mindset