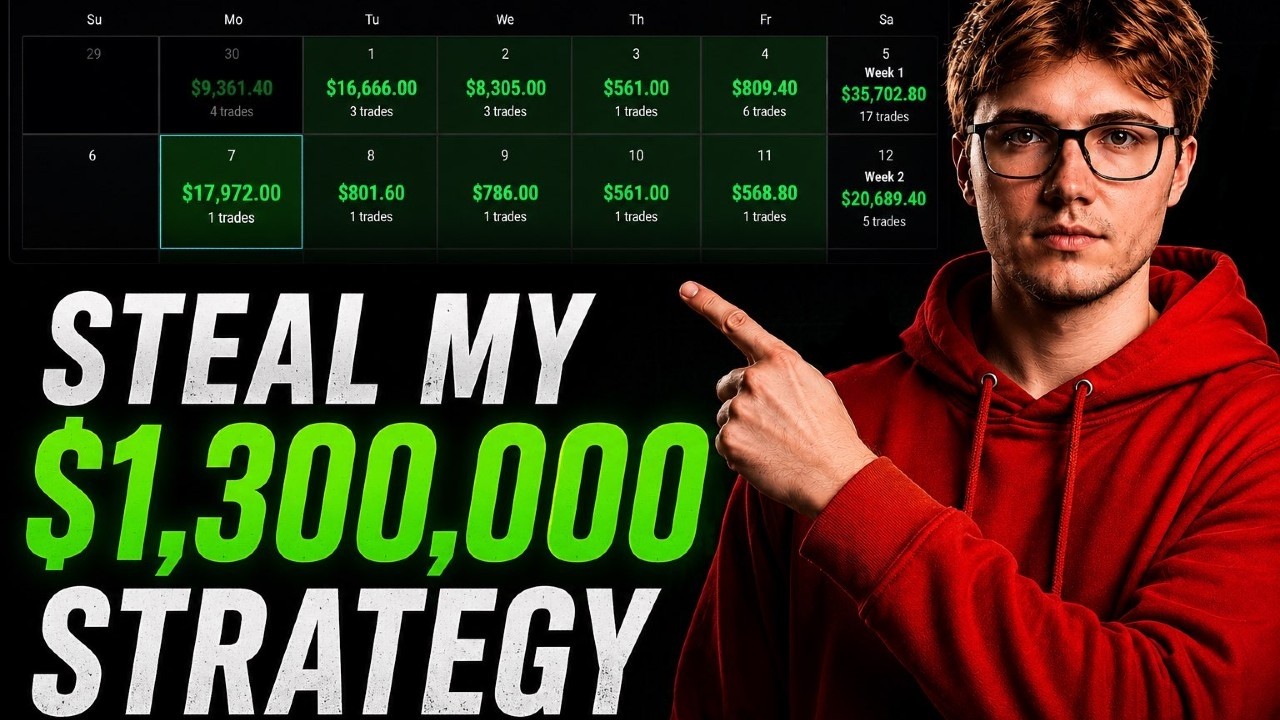
JJ Simon reveals a $1.8M prop firm trading strategy optimized for prop firm rules, focusing on bias and risk management for higher pass rates.
Key Takeaways
- Prop firm trading requires strategies optimized for their unique rules, not live market conditions.
- A bias-based mean reversion strategy improves pass rates by providing a consistent edge.
- Optimizing profit targets and stop losses for prop firm rules maximizes expected value and payout chances.
- Discretionary take-profit and stop-loss strategies designed for live markets often fail in prop firm environments.
- Frequent trade attempts with a slight edge and proper risk management yield better results on prop firms.
What the video covers
- Most trading strategies fail on prop firms because they are designed for live markets, not the specific rule sets of prop firms.
- JJ Simon has earned $1.8 million in profit payouts by optimizing his strategy specifically for prop firm environments.
- The strategy focuses on optimizing pass rate and expected value rather than traditional return metrics like Sharpe ratio.
- The core strategy is a mean reversion approach based on a market bias, such as reversion to session open or pre-news prices.
- Having a bias is crucial because it provides a slight edge and allows consistent optimization of profit targets and stop losses within prop firm rules.
- Prop firms have rules designed to make traders fail, so live market strategies often lose expected value when applied directly.
- The strategy uses break of structure entries to add a slight edge and maximize trade attempts throughout the day.
- Optimizing take profit and stop loss for the prop firm’s specific profit target and max loss rules increases the chance of passing evaluations.
- Trades are sized and executed to maximize expected value given the prop firm’s payout structure and risk limits.
- The approach is adaptable to different prop firms and account sizes by adjusting profit targets and stop losses accordingly.
Full Transcript — Download SRT & Markdown
Speaker A
Most trading strategies fail on prop firms because they're built for live markets. But prop firms are not live markets. They also have specific rules designed for you to fail. So here's why your strategy doesn't work and mine does. I have $1.8 million in profit payouts to back that claim. Here's $180,000 from Tradeify 167 funded next E8, my funded futures loose trading and top. My entire approach has been optimizing my strategy and my risk management for the prop firm specific environment. A live trading strategy would optimize for the return or the Sharpe ratio. But when you plug into a prop firm, you want to optimize for your pass rate, which is your chance of reaching your profit target before your max loss. Then on the funded account, optimize for your expected value, which is basically your chance of getting a payout multiplied by how large that payout is. So it no longer becomes a problem that you have to solve and optimize for in terms of returns. It is now a specific rule set optimization problem, which gives you a much different answer. So the main strategy that I trade is a mean reversion strategy that is built on a bias. We are going to assume a specific fair price in the market, which would be a session open or a pre-news event. In this example here, this is a news event at 8:30 a.m. Eastern. It is essentially priced in, in my opinion. So, this huge move down is unfair, and I'm going to look for reversions back to that pre-news price. As you can probably tell, the bias is longs back towards this pre-news price. But why is a bias so important on a prop firm specific environment? Well, imagine this is your bias on the market. Obviously, it's not going to be this linear, else you would have an extreme edge, which is not even possible. So, imagine you have a slight edge in the direction of your bias. This specifically is going to work better on a prop firm than any trading strategy that is taking one-off entries with specific profit targets and stop losses. You have to have a bias the entire way so that your account is realizing the same amount of bias on each trade that you take. The reason why is because you're given a specific rule set, and within that specific rule set, whatever rules you have to abide by, there must exist a statistically optimal profit target and a statistically optimal stop-loss to exist within those environments at any given win rate or risk-to-reward. So, if you're tasked with making 3,000 before minus 2,000, going for $1,000 of profit or 1,500 profit or 300 profit are all going to have different pass rates because they're fitting into the rules differently as the drawdown trails. So the best approach on a prop firm is to find the one that has the highest pass rate specifically and then execute that as many times as possible. That is why it is so important to have a bias because anytime you have a bias, that means you have a very slight edge. And if you're able to optimize these values for the prop firm specific environment and realize your edge at the same time, then you're going to be making a lot of money on the prop firm specific environment because it's optimized for the rules. You could also use any profit target because you're obviously going to be trading on a different prop firm at different times. So if you're thinking the fair price is here and you're looking for a reversion to that area, entering here is going to give you maybe 100 points in your favor, but entering all the way up here is only going to give you 10 points in your favor. So these are very different trades, and they should be implemented on different prop firms or the same prop firm but with an account that is worth a different amount of expected value or an account that needs a different profit target based on its status. Now you're probably wondering why did I say your strategy is not going to work on a prop firm specific environment. The reason for that is you most likely are trading on discretionary take-profit stop-losses. So maybe you see an entry here, and your take profit is this previous high for whatever reason that your strategy believes in. Fine. And then your profit target is going to be maybe exactly $350, and your stop loss is going to go below this low to be risking $270. That's fine. You're definitely working to optimize your strategy's return. But this would work best on a live account. When you're given a prop firm specific rule set, these values are nowhere near optimal, and you don't even know what the optimal value is. So, you're losing a bunch of expected value by fitting your strategy to a live market, throwing it in, and hoping the prop firm rules allow it to work. Remember how much money prop firms make, and that's because prop firms make money when you lose. So, they have to structure the rules in which a prop firm strategy would win, but a live account strategy would lose. So, if you have an optimized live account strategy and you plug it into the prop firm, it is not going to make money just because prop firms have optimized for that, and they understand most traders are doing that incorrectly, which is how they can make so much money on your eval fees. Another benefit to a biased or mean reversion strategy is if you assume your bias in this day would be a reversion to the market open. This is the day I'm recording, Tuesday, September 8th. If there is a bias in your favor of a mean reversion trade, then you could get the same effective bias with an entry here as you could with an entry all the way here. Because it's a bias, you're expecting linear, very, very slight linear drift from the current point in time. No matter where you're entering, even if you're entering here, you're still expecting a slight linear drift. It might even be this linear. It definitely is not this linear. It might even be slight, like 1% edge. The most important part is that it is a bias. So you could be entering trades at any point along this move up. Then your take-profit and stop loss are optimized for the prop firm specific rule set that you have been given. So now that means I'm able to get in a ton of trade attempts. So now let me go into the strategy that I trade. Now hopefully you believe why it works best on the prop firm environment and why it works better than other strategies just because everything is fit to the rule set because you're given a bias. You can optimize your take profit and stop loss because they're all going to generate the same EV in a biased environment. So, we're assuming the strategy is the same EV. If we do this take profit stop loss and if we do this take profit stop loss because it's a bias, so it's slightly winning above break even. Compare this to break even, but you have the bias for your take profit. Same thing with this. Compare this to a slightly above break even. You're going to have the bias plus this take profit and this stop loss are then set specifically for the prop firm environment. So, now that we've done all that, we've optimized everything as best we can. Let's talk about the specific strategy and how you can make your bias correct because the bias is the most important part. The entries can add a very slight amount of edge, 0.1%. It is always worth adding edge if you're able, which is why I trade this specific entry model of break of structure entries just because it adds 0.1% edge. So I mean, might as well. Most importantly though is your prop firm specific targets. And I'll also show you how I'm able to get in so many trades throughout the day. So I'm going to assume the market is opening at a fair price. So market open, there's an influx of volume. Institutions begin trading, and it is going to create a very large unfair move away. I'm going to look for reversions back to the market open, and my entry criteria is two things. First, break of structure, which is, I believe, the standard definition. I don't really keep track with other traders, but if you have a wick here and this candle breaks above the wick because this one is taller than...
Speaker A
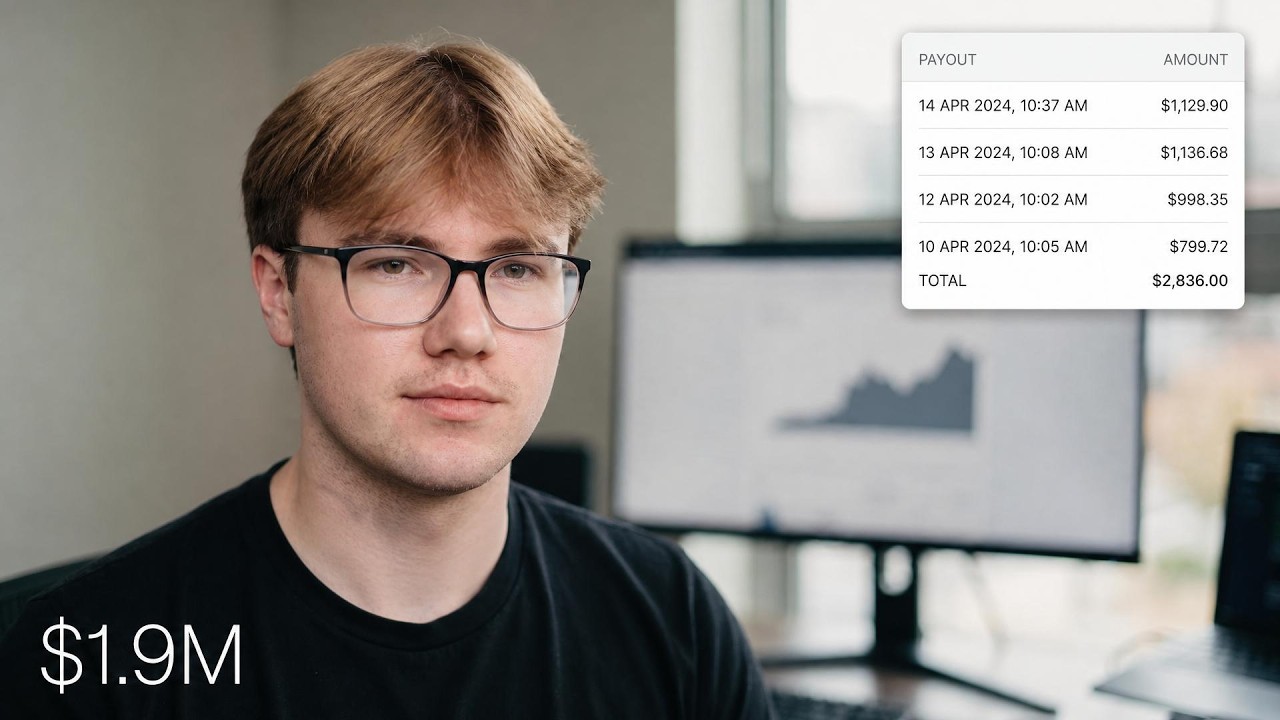
payouts to back that claim. Here's $180,000 from Tradeify 167 funded next E8 my funded futures loose trading and top. My entire approach has been optimizing my strategy and my risk management for the proper specific environment. A live trading strategy
Speaker A
would optimize for the return or the sharp ratio. But when you plug into a prop firm, you want to optimize for your pass rate, which is your chance of reaching your profit target before your max loss. Then on the funded account,
Speaker A
optimize for your expected value, which is basically your chance of getting a payout multiply by how large that payout is. So it no longer becomes a problem that you have to solve and optimize for in terms of returns. It is now specific
Speaker A
rule set optimization problem, which gives you a much different answer. So the main strategy that I trade is a mean reversion strategy that is built on a bias. We are going to assume a specific fair price in the market, which would be
Speaker A
a session open or a pre-news event. In this example here, this is a news event at 8:30 a.m. Eastern. It is essentially priced in in my opinion. So, this huge move down is unfair and I'm going to look for reversions back to that
Speaker A
pre-news price. As you can probably tell, the bias is longs back towards this pre-news price. But why is a bias so important on a profit specific environment? Well, imagine this is your bias on the market. Obviously, it's not
Speaker A
going to be this linear else you would have an extreme edge, which is not even possible. So, imagine you have a slight edge in the direction of your bias. This specifically is going to work better on a prop firm than any trading strategy
Speaker A
that is taking oneoff entries with specific profit target and stop losses. You have to have a bias the entire way so that your account is realizing the same amount of bias on each trade that you take. The reason why is because
Speaker A
you're given a specific rule set and within that specific rule set, whatever rules you have to abide by, there must exist a statistically optimal profit target and a statistically optimal stop-loss to exist within those environments at any given win rate or
Speaker A
risk-to-reward. So, if you're tasked with making 3,000 before minus 2,000, going for $1,000 of profit or 1,500 profit or 300 profit are all going to have different pass rates because they're fitting into the rules differently as the draw down trails. So
Speaker A
the best approach on a prop firm is to find the one that has the highest pass rate specifically and then execute that as many times as possible. That is why it is so important to have a bias because anytime you have a bias that
Speaker A
means you have a very slight edge. And if you're able to optimize these values for the prop from specific environment and realize your edge at the same time then you're going to be making a lot of money on the prop from specific
Speaker A
environment because it's optimized for the rules. You could also use any profit target because you're obviously going to be trading on a different prop firm at different times. So if you're thinking the fair price is here and you're
Speaker A
looking for a reversion to that area, entering here is going to give you maybe a 100 points in your favor, but entering all the way up here is only going to give you 10 points in your favor. So
Speaker A
these are very different trades and they should be implemented on different prop firms or the same prop firm but with an account that is worth a different amount of expected value or an account that needs a different profit target based on
Speaker A
its status. Now you're probably wondering why did I say your strategy is not going to work on a proper specific environment. The reason for that is you most likely are trading on discretionary take-profit stop- losses. So maybe you
Speaker A
see an entry here and your takeprofit is this previous high for whatever reason that your strategy believes in. Fine.
Speaker A
And then your profit target is going to be maybe exactly $350 and your stop loss is going to go below this low to be risking $270. That's fine. You're definitely working to optimize your strategy's return. But this would work
Speaker A
best on a live account. When you're given a profit specific rule set, these values are nowhere near optimal and you don't even know what the optimal value is. So, you're losing a bunch of expected value by fitting your strategy
Speaker A
to a live market, throwing it in, and hoping the prop firm rules allow it to work. Remember how much money prop firms make and that's because profers make money when you lose. So, they have to structure the rules in which a prop firm
Speaker A
strategy would win. But a live account strategy would lose. So, if you have an optimized live account strategy and you plug it into the prop firm, it is not going to make money just because profirms have optimized for that and
Speaker A
they understand most traders are doing that incorrectly, which is how they can make so much money on your eval fees.
Speaker A
Another benefit to a biased or mean reversion strategy is if you assume your bias in this day would be a reversion to the market open. This is the day I'm recording Tuesday, September 8th. If there is a bias in your favor of a mean
Speaker A
reversion trade, then you could get the same effective bias with an entry here as you could with an entry all the way here. Because it's a bias, you're expecting linear, very, very slight linear drift from the current point in
Speaker A
time. No matter where you're entering, even if you're entering here, you're still expecting a slight linear drift.
Speaker A
It might even be this linear. It definitely is not this linear. It might even be slight like 1% edge. The most important part is that it is a bias. So you could be entering trades at any point along this move up. Then your
Speaker A
take-profit and stop loss are optimized for the profer specific rule set that you have been given. So now that means I'm able to get in a ton of trade attempts. So now let me go into the strategy that I trade. Now hopefully you
Speaker A
believe why it works best on the profer environment and why it works better than other strategies just because everything is fit to the rule set because you're given a bias. You can optimize your takeprofit and stop loss because they're
Speaker A
all going to generate the same EV in a biased environment. So, we're assuming the strategy is the same EV. If we do this take-profit stop-loss and if we do this take-profit stop-loss because it's a bias, so it's slightly winning above
Speaker A
break even. Compare this to break even, but you have the bias for your take-profit. Same thing with this.
Speaker A
Compare this to a slightly above break even. You're going to have the bias plus this take-profit and this stop-loss are then set specifically for the profit environment. So, now that we've done all that, we've optimized everything as best
Speaker A
we can. Let's talk about the specific strategy and how you can make your bias correct because the bias is the most important part. The entries can add a very slight amount of edge 0.1%. It is always worth adding edge if you're able
Speaker A
to which is why I trade this specific entry model of break of structure entries just because it adds.1% edge. So I mean might as well. Most importantly though is your profit specific targets.
Speaker A
And I'll also show you how I'm able to get in so many trades throughout the day. So I'm going to assume the market is opening at a fair price. So market open there's an influx of volume.
Speaker A
institutions begin trading and it is going to create a very large unfair move away. I'm going to look for reversions back to the market open and my entry criteria is two things. First, break of structure which is I believe the
Speaker A
standard definition. I don't really keep in track with other traders but if you have a wick here and this candle breaks above the wick because this one is taller than the two next to it, it is structure. When this shoots up beyond it
Speaker A
and closes, then the structure is being broken. So that is a break of structure entry back towards the market open. This would be the first entry criteria. Now, I obviously have multiple because I'm trying to get through a bunch of trades
Speaker A
per day. Also, multiple trades per day is a very good thing because you can spread your risk and it's not all placed on one trade. I know a lot of people take one trade a day. Please don't do
Speaker A
that. I mean, maybe do it on a live account, but please not on a prop firm.
Speaker A
You're never going to be able to scale. So, entry criteria for a displacement candle is the body of the candle is larger than the body of the previous candle and it closes above the wick of the previous candle. So, here's a very
Speaker A
obvious displacement. Body is larger and here's the wick. This one clearly closed above. So that is a possible displacement candle entry. Now maybe you're wondering where do I put my stop loss? Where do I put my profit target?
Speaker A
Well, it's based on exactly what my account wants. So maybe I have an account that needs a 50 point win and it has a 25 point stop loss with one contract, two, three, whatever. That's exactly what it's going to be. The only
Speaker A
thing I will not do is I will not trade beyond this red line. I will sometimes, but I need 80% of my trade to be below the red line. I do not want to trade more than 20% of my trade's profit
Speaker A
target away from fair value. Fair value is a very strong bias that wins above break even rates which is why it works so well on proper environments. But obviously you have to be getting the fair value price correctly. You could
Speaker A
use VWOP. It is a pretty good estimate on average. You could honestly just solely trade in the direction of VWAP and you would be expecting to make a ton of money on a proper environment assuming you have optimized
Speaker A
risk and profit targets. But the only problem is VWOP doesn't really accurately account for news. So that's why I personally don't use it. I just rely on a little bit of discretion to identify fair value. But basically, I'm
Speaker A
just going to assume it's the market open trading reversions in that direction. Then if it ever makes a displacement break of structure away from the open like it does here, then I would adjust it to the most recent
Speaker A
price. Then in here, there is no real break of structure, no continuation away. It's just 1 2 3 four failed attempts to go short. This one is like an obvious attempt to go short and it succeeded going short. So I might adjust
Speaker A
it to this area here, which is in line with VWAP. Um, but anyways, then I'm looking for reversions back to this price. Now, like I said multiple times, I'm not taking a 78 point take-profit. I will be doing 50, 45, 70, whatever my
Speaker A
account needs specifically for the optimized value in its specific rule set. And also, by the way, it changes on a prop firm. So, if I'm on an eval with Topep, that's a different RR, different profit target, different stop-loss than
Speaker A
a funded with Topep, which is different than a funded account that is new, different than a funded account that is in loss, different than a funded account that is in profit, different than a funded account that's taking a payout.
Speaker A
So, tons of optimizations you should do. Do not feel overwhelmed. Feel excited that there are so many optimizations that you can do. If you are break even right now, that is amazing. If you're break even on a prop firm, you can get a
Speaker A
3x return on your investment. I'm I'm very confident in you on that. Anyways, I'll show a little bit more of the entries just because they do add a little bit of edge to the strategy specifically. Obviously, the most
Speaker A
important part is the bias. So, let's see. Displacement candle entry would be right here for the first one. Then you get another displacement candle entry right here because this one is larger than the previous one and it closed
Speaker A
above the wick. Then this candle here is breaking this structure. After that, another displacement here and then another break of structure up here. So, not the best start today, but obviously not done. Also, you can take slightly higher quality setups where the trend is
Speaker A
more confirmed and that is going to increase your win rate slightly. I don't bother saving my accounts for that because there's only going to be a few of those stronger trades per day. And my real goal per day is to just get all of
Speaker A
my accounts traded in the direction of my bias because speed is key on proper.
Speaker A
So there's another displacement. And then there's another displacement. Now we're finally going to start winning.
Speaker A
Okay. So we took one, two, three, four, five losses. Seems like a lot, but it's fine because you have a direction of the bias. So here's the first win off displacement. Here's the next win off break of structure. You
Speaker A
could obviously layer in more aggressively. I do. Um, anytime I see a green candle, I'm just going to layer in. Um, if you see a green candle, then there's a 50.5% chance the next candle is green. So do with that what you will.
Speaker A
Um you get another break of structure here. Then you get another break of structure. Oh, then you get another break of structure here. Then you get another break of structure here. And then another one here. And then another
Speaker A
one here. And then another one here. I guess you could maybe call it at the red line. Don't trade above the red line.
Speaker A
Probably not. I did take one trade up here. Um but slightly more biased towards this red line which it is consolidating at now. I don't know what this is. Um, but anyways, you get a bunch of wins when it's trending in your
Speaker A
favor, which is always great. Uh, most important thing is the bias though. Let me show you on a news day. This here is modeled on a news day. I believe today's Tuesday the 8th. Monday was the bank holiday. Friday we had news. So, let me
Speaker A
show you Friday. So, assuming fair price is going to be the pre-news price. I'm looking for reversions to the pre-news price. That is the direction of my bias.
Speaker A
Then I fit that to the profit specific take-profit stop-loss and it's going to print me money. So, there's the first one. um your takeprofit and your stop loss again depending on your account.
Speaker A
Another one there displacement and then breakup structure here. Breakup structure where is it here and then another one here and then another one here and then a final one up here. So same thing just a bias for reversion and then fitting
Speaker A
that to the specific rule set that you're given with optimized take-profit stop-loss values. Um, it does get obviously a little bit more complicated than that because those values, the optimized values do change based on a few factors. What firm you're on,
Speaker A
evaluated, and current balance/draw down. Uh, they're kind of the same thing. Um, basically like how much is your account worth and how much will it be worth in the future if you win a trade for $1,000. How much will your
Speaker A
account be worth? What is your chance of winning that trade multiplied by how much it's worth subtracted by if you lose a,000? Now, how much is your account worth multiplied by the chance you lose that trade. So just simple
Speaker A
expected value calculations like that formulas online. So in total I have done 1.818 I think it's 56 it might be a little bit more at the time of recording but how much have I spent on evaluations? About $557,000.
Speaker A
So definitely a lot but the thing is I started with 5,000. So if you look at this return it's a 3.5x return. I also have money still in my accounts that I could withdraw obviously without spending anymore. So, my return
Speaker A
would probably go up to like 3.8 or 4x maybe. But anyways, 3.5x return on my investment. Uh, which is great. Please name another investment that's going to give you 3.5x return. Uh, basically none. But how much did I start with?
Speaker A
$5,000. I made $17,000 from my $5,000 investment. I actually have the proof over here. Um, maybe you saw this other video from me, but anyways, this is from 2025 last year and February was my first month that I started trading. I made
Speaker A
nothing then and nothing then. and I had no money. Um, and then this is 17K. So, I made 17K back like payouts and I spent 5,000 to achieve that. Then the next month after that seems to be like 38,000
Speaker A
and then 46K. Um, and then May finished a lot higher than that. May finished at 84K. June smaller one, but then first six figure month in July. So, when people cringe originally, I tell them I spent $550,000 on eB. They're like,
Speaker A
"What the hell? I don't have $550,000." Well, yeah. Neither did I. I started with $5,000. Now I'm at 1.3 million in profit with more in my accounts. Like I could withdraw 200k from my accounts and never spend another dime and then I
Speaker A
would have done 500 to 1.5 mil in a year and a half. So like it's it's insane returns. Please make sure you approach the prop firms optimally. Even if you don't want to work with me, approach the prop firms optimally. Here was the
Speaker A
original investment 57. So 3.5x and it's still about 3.5x because pretty much nothing has changed with the proper environment. If you're interested in learning directly from me to see exactly how I did 5 mil 5,000 to 1.8, then apply
Speaker A
to work with me at the link in the description. Like I said, I will be going over the entire strategy more in depth. But obviously, most importantly, the profit specific risk. So, which platform we're on, what our balance is,
Speaker A
what our draw down is, if we're evaluate the most expected value given our rule set. That is what I studied in college, quantitative finance. And now that is what I teach the optimal properform approach with this strategy. If you're
Speaker A
interested in learning from me, top link in the description.
Topics:prop firm tradingmean reversion strategytrading biasrisk managementpass rate optimizationexpected valuefunded traderbreak of structuretrade optimizationJJ Simon